The National Bureau of Statistics has reported that Nigeria’s headline inflation rate fell to 14.63 per cent in October 2026, down from 15.39 per cent in August. According to figures released in mid-October, that is the lowest reading since October 2020, which means prices are now rising at their slowest annual pace in close to six years.
It is a significant milestone for an economy that was battered by the removal of fuel subsidy, the unification of the exchange rate and years of currency weakness. Yet as any trader in Mile 12 or Balogun market will tell you, a slower rise in prices is not the same as falling prices. The economy is cooling, but the cost of living is still high.
The month-on-month picture is where the story gets more interesting. The NBS said headline inflation on a monthly basis slowed to 0.06 per cent in September, compared with 0.71 per cent in August. In plain language, the average basket of goods and services barely moved in September. That is a sharp change from the sort of monthly jumps Nigerians had grown used to, and it suggests the easing is not merely a statistical effect from a high base a year ago.
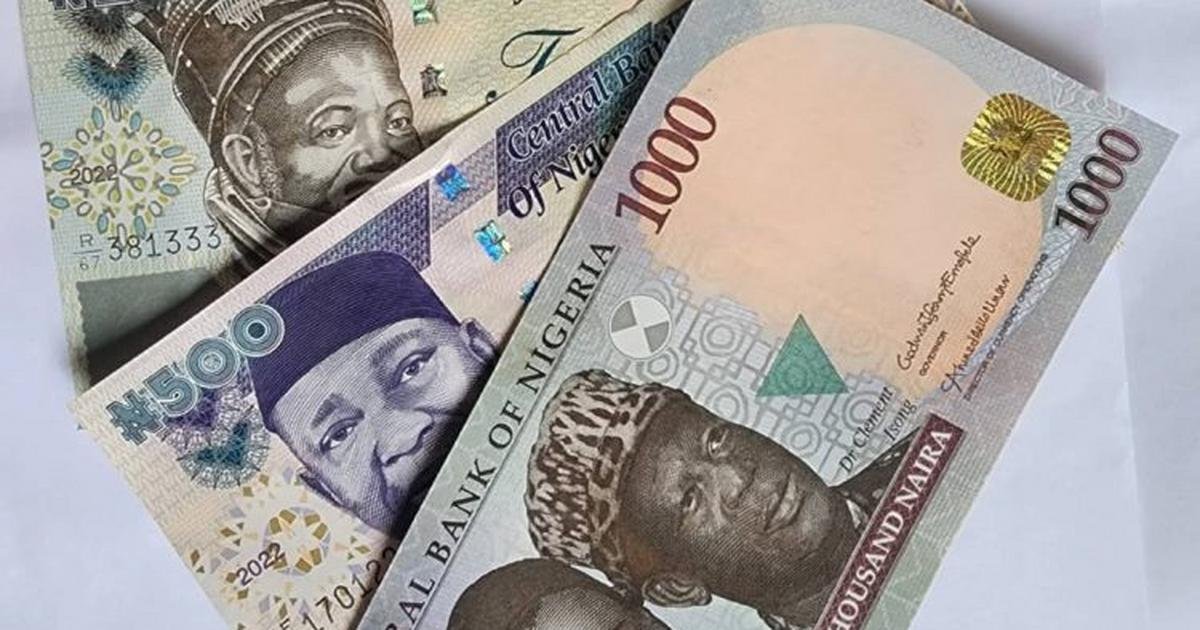
Analysts who track the data say the main support has come from the naira. The currency has traded in a relatively narrow band for months, and that stability has reduced the pressure on imported goods, from machinery and fuel to the many food items and household products that Nigeria still buys abroad. A mid-year outlook report by PwC’s strategy arm put the official rate at about 1,380 naira to the dollar in June, with the parallel market only a few naira away. When the gap between official and street rates narrows, importers and retailers have less reason to pad their prices against uncertainty.
Still, the headline number hides a stubborn spot. Food inflation, which carries the largest weight in the consumer price basket, remains close to 20 per cent. Figures for August put it at 19.57 per cent, and the September data points to a similar level of around 19.6 per cent. That matters because food is where Nigerian households feel inflation most directly. A family that spends well over half of its income on food does not experience a 14.63 per cent headline rate. It experiences the price of a congo of rice, a paint bucket of beans, a tuber of yam and a bottle of vegetable oil, and those prices have not eased in step with the headline figure.
There is a seasonal and structural story behind this. Insecurity in farming communities has kept many growers away from their land, transport costs remain high, and storage and logistics losses eat into supply. Until those problems are tackled, food prices will remain the weak link in the disinflation story, whatever the monetary and exchange rate picture looks like.
The inflation data arrives at a time when the wider economy is also showing better numbers than it has in years. Official figures show that Nigeria’s economy grew by 4.43 per cent in the second quarter of 2026, its fastest pace in about five years. Manufacturing, agriculture and services led the expansion, while the oil sector benefited from higher crude prices tied to tension in the Middle East. Over the 12 months to June, the naira also gained about 12 per cent against the dollar, according to reports on the data, and foreign direct investment inflows improved.
That combination of stronger growth, slower price increases and a steadier currency is the outcome the Tinubu administration has said its reforms were designed to deliver. Government officials have repeatedly argued that the pain of the early reform years would give way to stability, and the September numbers will be cited as evidence that the argument is holding.
Economists, however, urge caution on three fronts.
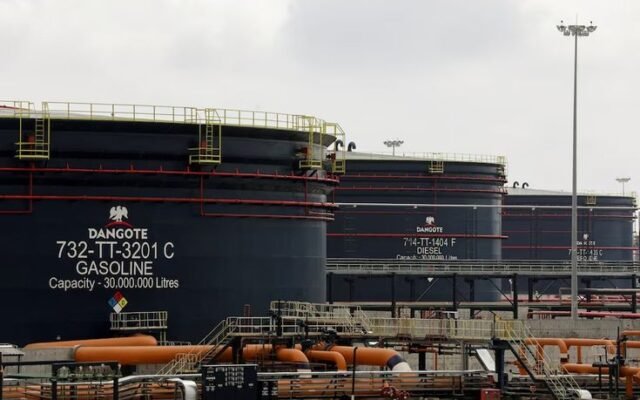
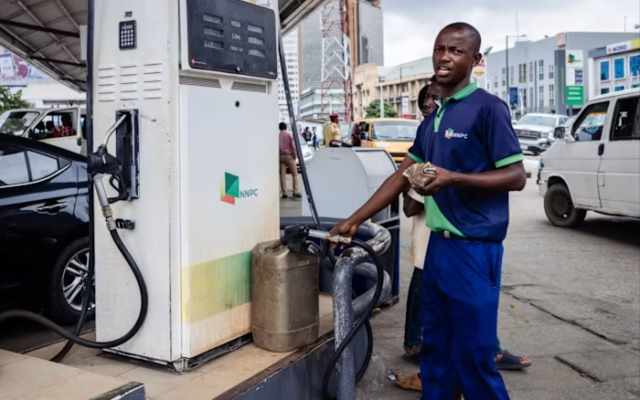
First, higher oil prices are a double-edged sword. They lift government revenue and foreign exchange earnings, which supports the naira. They also push up the cost of diesel, petrol, freight and power for businesses, and those costs eventually show up on shelf prices. PwC’s outlook warned that elevated crude could feed imported inflation even as it helps the national purse.
Second, government revenue has struggled to keep pace with ambition. The same outlook report noted that gross tax revenue in the first quarter rose by more than 23 per cent year on year, but still fell short of the official target, leaving a gap of about 2.24 trillion naira. A shortfall of that size can force more borrowing, and heavy borrowing tends to keep interest rates high and leave less room for the private sector to expand.
Third, the political calendar. With the next general election cycle approaching, analysts have warned that pre-election spending could push money into the economy faster than goods and services can match it. That is a classic recipe for renewed price pressure, and it is one reason forecasters expect disinflation to continue but at a gradual pace rather than a dramatic drop.
Interest rates tell the same story. The Central Bank of Nigeria held its benchmark rate at 26.5 per cent at its May meeting after trimming it by 50 basis points in February, citing persistent food inflation and external risks. With headline inflation now below 15 per cent, the gap between the policy rate and inflation is wide, which will fuel calls for the central bank to ease further. Businesses that borrow to finance stock, equipment or expansion are among the loudest voices making that case, since loans priced in the high twenties and beyond make it hard to invest. The monetary policy committee, for its part, will want to be sure that the price slowdown is durable before it loosens policy in earnest.
For ordinary Nigerians, the practical question is simple: when does this reach my wallet? The honest answer is slowly and unevenly. Salaried workers who negotiated increases in the past two years may begin to feel some relief as price growth moderates. Small traders may see more predictable restocking costs if the naira holds. But for low income households, whose spending is dominated by food and transport, the relief will be limited until food prices come down in a lasting way.
There is also a psychological factor. Inflation expectations shape behaviour. When people believe prices will keep jumping, they hoard, raise prices early and demand bigger pay rises, which can keep inflation elevated. A run of lower readings, backed by a stable naira, can slowly reset those expectations. That is why the consistency of the trend over the coming months will matter as much as the headline figure itself.
What should readers watch next? The October inflation report, due in mid-November, will show whether the September slowdown was a one-off or the start of a firmer trend. The naira’s behaviour in the weeks ahead, the direction of global crude prices, the central bank’s next rate decision, and the progress of the harvest season will all play a role. Any sudden jump in fuel prices or a fresh round of currency pressure could quickly undo the gains.
For now, the September figure stands as the clearest sign yet that Nigeria’s macroeconomic stabilisation is producing results on paper. Whether Nigerians feel it in the market, at the pump and at the dinner table will decide how the numbers are judged. The economy has turned a corner on inflation. The task now is to make sure the corner leads somewhere households can actually feel.